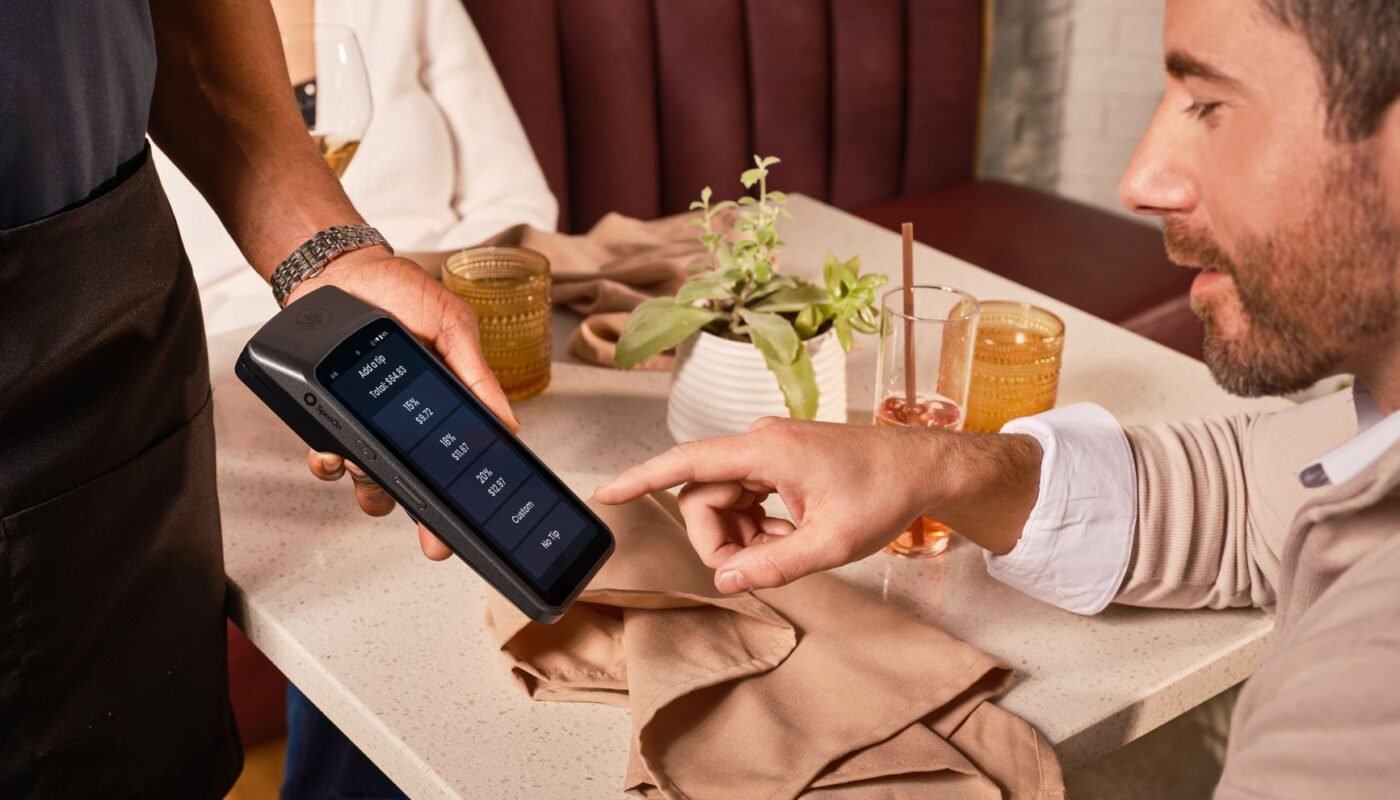

Shift4 reported on November 5 that payments-based revenue, after network fees, grew 18% in the third quarter to $402 million, while its subscription and other revenue fell 10% to $107 million. For restaurant and hotel operators who run Shift4’s point of sale, the shift matters because the company’s chief executive described it as a deliberate strategy.
The figures come from Shift4’s third-quarter shareholder letter, filed with the SEC as Exhibit 99.1 to an 8-K. Volume processed reached $61 billion, up 11% from a year earlier. Gross revenue was $1,319 million, up 12%, and gross revenue less network fees was $648 million, up 10%. Net income was $40 million.
What the letter says about the revenue mix
Shift4 splits its revenue less network fees into three lines. Payments-based revenue was $402 million, up 18%. Tax-free shopping, the business it gained with Global Blue, brought in $139 million, up 7%. Subscription and other revenue, the line that covers software fees, was $107 million, down 10%.
Advertisement
Chief Executive Taylor Lauber addressed the mix directly in the letter: “We continue to see opportunities to trade single product revenue for higher quality payments-based revenues and will do that as aggressively as we can.” Shift4 calls payments-based revenue less network fees its “north star” and says it grew 23% year to date.
The letter ties the software line to hardware and acquisition cost. Under customer acquisition, Shift4 lists eliminating upfront costs for merchants by providing essential hardware, and providing financial incentives to align its partners and salespeople. The letter does not say how those costs are recovered from a merchant over the life of a contract.
Guidance cut, with same-store sales named
Lauber called the quarter “a more challenging backdrop than we’ve seen in recent years.” The letter says same-store sales “continued to face pressure off reasonably low comparables” and that travel disruption, which weighs on tax-free shopping, has been more pronounced in the fourth quarter.
Shift4 lowered its full-year 2026 gross revenue less network fees guidance to $2.45 billion to $2.46 billion and adjusted EBITDA to $1.11 billion to $1.13 billion. By the letter’s own count, that is roughly 4% and 6% below the original full-year guidance. Volume guidance is now $240 billion to $250 billion, with the upper end tightened, and adjusted free cash flow of $465 million to $475 million was affirmed.
The letter lists travel disruption, currency, inflation and same-store sales as the headwinds. Volume still grew 11% in the quarter, so the pressure appears in the guidance and in the revenue lines, not in a fall in volume.
New hospitality customers and a pay-by-bank deal
On the customer side, Shift4 says it signed Kahala Brands, “now our single largest restaurant customer,” added the MSG Sphere and several European hotels, and introduced enterprise loyalty for hospitality. It also released multi-location enhancements and a quick-service feature set within Shift4 Dine, and a unified analytics product, Location Manager 2.0.
Shift4 also announced a pending acquisition of Paramount Commerce, a Canadian account-to-account payments platform. The letter lists same-day tip payouts for dining and lower-cost settlement on high-ticket bookings for hotel stays among the uses for pay-by-bank. The deal had not closed when the letter was published.
Where the cash is going
Shift4 reports a record quarterly adjusted free cash flow of $200 million. It repurchased 4.2 million shares for $190 million in the quarter, and the letter says a further $1 billion authorization was recently approved. It also says it expects to exit the year with nearly $50 million in synergies from Global Blue, against a 2027 target of $70 million. The letter describes new hospitality products and customer wins alongside those buybacks, which is the context for the pricing questions below.
What it means for operators
Restaurant groups and hotel owners on a Shift4 contract, or comparing it with others, have three questions to put to any processor with this mix.
Where the software fee went. If a vendor’s subscription line is shrinking while its payments line grows, the cost of the system can move from a monthly fee to the processing rate. Ask for the effective rate and the software fee quoted separately, then compare the two quotes on total annual cost at your own volume.
How free hardware is paid back. Terminals supplied without an upfront charge are repaid through the term, the rate or an early termination fee. Ask which, and what leaving in year two costs.
What happens if sales fall. The processor’s guidance now assumes weak same-store sales into the new year. A contract priced on a volume tier can look different for an operator whose sales are flat, so check minimums and tier resets.
Other hospitality software vendors have reported on payments recently. Lightspeed reported payments at 45% of its volume after selling Upserve, and Toast added 8,500 net locations in the third quarter as growth slowed to 21%. In our reading, that makes the processing rate the figure to compare across the three vendors when a contract comes up.
What to watch
Lauber says he believes the headwinds “will abate in the times ahead.” Operators renewing in the next two quarters should ask for the rate and the software fee as separate lines, and read the term and termination clauses before the hardware discussion starts.
Source: Shift4 Payments, Q3 2026 shareholder letter (SEC Exhibit 99.1)